TL;DR
In short
- Most insurers treat you as a smoker if you have used tobacco or nicotine products in the past 12 months.
- For most insurers, occasional smoking counts the same as heavy smoking when deciding whether you are a smoker, and e-cigarettes and other nicotine products usually count too.
- Smokers can buy life insurance in the UK, but premiums are significantly higher for smokers and the gap tends to widen with age.
- You must take reasonable care to answer the insurer’s questions fully and accurately, including about any tobacco or nicotine use.
- Once you have been nicotine-free for 12 months, you may be able to apply for new cover at non-smoker rates.
Smoking cigarettes is harmful to health - every healthy-minded person knows this. Although the smoke from burning cigarettes causes cancer and increases the risk of heart attack, stroke and sight loss, about 4.9 million UK adults (2025) struggle with the habit. That’s a huge group of people, so inevitably, insurance companies are forced to tailor their offers to smokers as well. In this article, we take a look at how smoking cigarettes affects your insurance situation.
Who will insurance companies consider a smoker?
For most insurers, occasional smoking counts the same as heavy smoking when deciding whether you are a smoker. Most insurers treat you as a smoker if you have used tobacco or nicotine products in the past 12 months.
Users of e-cigarettes, pipes, cigars, hookahs and nicotine sachets are also considered smokers. In other words, anything that involves taking nicotine or inhaling smoke is considered smoking. Of course, this is a general rule, and each insurance company may regulate this issue differently - it is definitely worth checking the general terms and conditions of your policy and asking your Extend Finance adviser about this issue.
How long after quitting will I be treated as a non-smoker?
Typically, a person who has not used tobacco products for 12 months or longer is considered a non-smoker.
Life insurance in the UK for smokers - is it possible?
Although smokers are higher-risk customers for insurance companies, they can purchase life insurance in the UK. However, premiums are significantly higher for smokers, and the gap tends to widen with age.
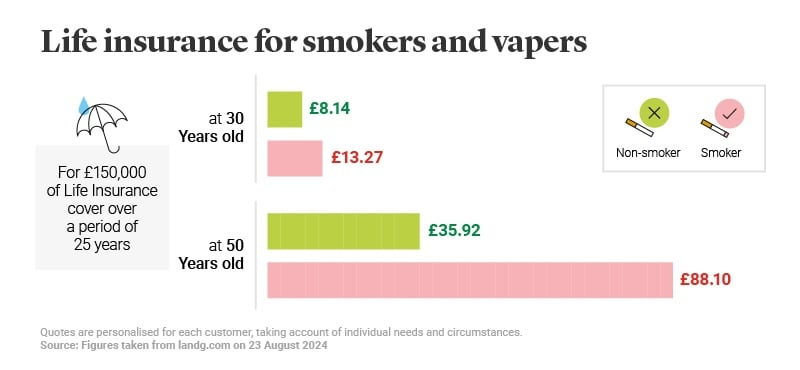
Source: Legal&General
How does the insurance company know that I am a smoker?
First and foremost, when you apply for life insurance in the UK, you must take reasonable care to answer the insurer’s questions fully and accurately, including about any tobacco or nicotine use. Inaccurate answers may affect a claim.
As Legal&General points out, the insurer may ask for your medical records.
When a claim is made, your insurer is likely to ask for the death certificate and may review your medical records. If you did not answer accurately, the insurer could reduce or refuse the payout, or cancel the policy, depending on whether the misrepresentation was careless or deliberate.
How much higher are life insurance premiums paid by smokers?
According to available calculations, the differences in insurance premiums are very pronounced:
| Age | Non-smoker | Smoker |
|---|---|---|
| 30 | £6.50 per month | £10.74 per month |
| 50 | £31.81 per month | £78.81 per month |
Illustrative quotes from mytribeinsurance.co.uk (2026 survey; £150,000 cover, 25-year term). Actual prices vary by insurer and personal circumstances.
The difference in premiums is large: in the example above, a 50-year-old smoker pays more than twice as much as a non-smoker. However, in setting the exact price, the insurer takes into account a whole range of factors, such as:
-
Your age;
-
Your health and medical history;
-
Whether you smoke or use nicotine;
-
Your lifestyle and occupation;
-
The amount of cover and the policy term.
What if I quit smoking?
Remember - it’s never too late to quit smoking cigarettes. Your decision will have a positive impact not only on your health, but also on your wallet: you won’t spend hundreds of pounds a year on cigarettes.
Quitting does not usually change the premium of an existing policy. Once you have been nicotine-free for 12 months, you may be able to apply for new cover at non-smoker rates, or ask your insurer whether it will review your rating. An insurer may ask for evidence, such as a medical report or a nicotine test. Keep your existing policy in place until any new one has started.
What can you do to pay less for life insurance if you smoke cigarettes?
Increased insurance premiums do not yet mean that you are not able to save money on your life insurance policy.
Contact a proven credit broker
You do not pay Extend Finance any fees for reviewing your insurance needs, providing insurance advice or arranging a policy. If you take out a policy through us, we receive commission from the insurer. You only pay the insurance premium for your chosen policy.
Consider whether you can influence other insurance parameters
Smoking clearly raises insurance premiums, but if you properly use the algorithms responsible for estimating risk, you may be able to reduce costs.
Probably the easiest way to reduce premiums is to give up extreme sports and high-risk occupations, reduce the coverage period and benefit amount. Even relatively small changes can translate into more preferential terms, and a smaller policy may be better than no cover at all.
Insure yourself as early as possible
The sooner you take out a life insurance contract, the better. Premiums generally rise with age, so it is not worth delaying.
Stop smoking cigarettes and take care of your health
Whichever way you look at it, smoking is harmful and expensive: it raises your premiums, costs hundreds of pounds a year and increases the risk of premature death. It’s never too late to quit, and your health will thank you for it.
FAQ
Frequently asked questions
Who will insurance companies consider a smoker?
Most insurers treat you as a smoker if you have used tobacco or nicotine products in the past 12 months. For most insurers, occasional smoking counts the same as heavy smoking when deciding whether you are a smoker, and users of e-cigarettes, pipes, cigars, hookahs and nicotine sachets are usually considered smokers too.
Life insurance in the UK for smokers - is it possible?
Yes. Smokers can buy life insurance in the UK, but premiums are significantly higher for smokers and the gap tends to widen with age.
How does the insurance company know that I am a smoker?
You must take reasonable care to answer the insurer’s questions fully and accurately, including about any tobacco or nicotine use, and the insurer may ask for your medical records. If you did not answer accurately, the insurer could reduce or refuse the payout, or cancel the policy, depending on whether the misrepresentation was careless or deliberate.
How much higher are life insurance premiums paid by smokers?
Premiums are significantly higher for smokers, and the gap tends to widen with age. In the illustrative quotes in this article, a 50-year-old smoker pays more than twice as much as a non-smoker; actual prices vary by insurer and personal circumstances.
What if I quit smoking?
Quitting does not usually change the premium of an existing policy. Once you have been nicotine-free for 12 months, you may be able to apply for new cover at non-smoker rates, or ask your insurer whether it will review your rating. Keep your existing policy in place until any new one has started.