TL;DR
In short
- UK lenders do not generally require customers to have life insurance, and there is no legal requirement to take out life insurance to get a mortgage.
- Most lenders do, however, require buildings insurance to be in place from exchange of contracts.
- For mortgage protection, the two main types of term life insurance are level term, where the cover stays fixed, and decreasing term, where the cover falls roughly in line with a repayment mortgage.
- Decreasing term cover usually costs less than level term cover, and premiums are usually fixed for the policy term.
- Cover matters most if you have dependants, a partner who could not repay the mortgage alone, or low savings compared with the mortgage balance; premiums depend on your age, health, BMI, occupation and smoking.
Lenders in the UK do not generally require customers to have life insurance, and it is an individual borrower’s decision to purchase it. It is up to you whether to have a policy, and a mortgage adviser can help you decide whether it is right for you. On the one hand, life insurance gives your family financial security in the event of your death. On the other hand, however, you have to pay the premiums. In this article, we’ll try to answer the title question by deciding whether it’s worth having a life insurance policy when paying off your mortgage in the UK.
Do banks offer better mortgages if you have life insurance?
Not really. UK lenders do not generally make life insurance a condition of a mortgage, including at the decision in principle stage. There is no legal requirement to take out life insurance to get a mortgage.
For example, HSBC states that you don’t need life insurance to get a mortgage. Most lenders do, however, require buildings insurance to be in place from exchange of contracts.
Your home is security for the mortgage, so if payments fall into arrears, the lender can ultimately take court action to repossess the home.
In summary, lenders do not generally require you to have a life insurance policy, but a mortgage adviser can help you decide whether cover is suitable for you. Insurance premiums are an ongoing financial commitment, so lenders may take them into account when assessing how much you can afford to borrow (your affordability).
Why is it worth having life insurance?
As we have already mentioned, buying life insurance is a matter of common sense and no one will force you to do so.
Life insurance is designed to provide financial security for your family when you die. In the case of a mortgage, the idea behind the policy is to pay out funds that will allow your loved ones to pay off your obligation. This can help prevent repossession, which could occur if there is a prolonged delay in paying instalments.
Buying life insurance is particularly recommended when:
-
Your partner is unable to repay your mortgage on their own;
-
You have dependent children, a partner or your parents;
-
The amount of your savings is small compared to the remaining mortgage balance;
-
You have taken out a mortgage with an LTV of 90% or 95%.
The more your family relies on your work, the more important it becomes to purchase a life insurance policy. Remember that after your death any debts are paid from your estate, and a joint mortgage remains payable by the surviving borrower. Life insurance will not protect you from an early death, but a payout can help your family clear the mortgage and stay in the home.
What insurances do I have to choose from?
For mortgage protection, the two main types of term life insurance are level term and decreasing term.
Level term life insurance
Level term life insurance is the most traditional type of policy - you take out cover for, say, 20 years, paying a set premium over that time. The sum insured, i.e. the amount of the potential benefit for your family, is set at the outset and, as a rule, does not change.
When you choose level term cover, each mortgage instalment you pay off increases the difference between the amount of the benefit and the balance of the debt. In effect, you are leaving behind a “legacy” of sorts. However, this comes at the cost of higher premiums.
Decreasing term life insurance
Another option is decreasing term life insurance, also known as mortgage life insurance.
The idea behind this policy is simple - with a repayment mortgage, you reduce your outstanding balance from month to month. Therefore, you don’t need the same protection throughout the repayment period - the cover decreases roughly in line with a repayment mortgage. Premiums are usually fixed for the policy term and lower than for level term cover, because the cover reduces.
Decreasing term life insurance can suit people who want to keep premiums down. It can be a lower-cost way to cover a repayment mortgage balance, although the payout may not exactly match the outstanding balance.
Are there situations where it is not worth buying life insurance?
There are scenarios where it is worth considering the cost-effectiveness of life insurance - sometimes it can be unnecessary or unaffordable, even if we have a family and a mortgage. What are these situations?
You have big savings
If you have enough savings that an emergency mortgage repayment in the event of your death would be possible, having a life insurance policy is not that necessary. Of course, few people have £250,000 in their bank account, but those with three, five or seven years left to repay have relatively little to repay. Let’s illustrate this with the example of a model repayment schedule for a £250,000 mortgage:
| Year | Outstanding balance |
|---|---|
| 0 (start) | £250,000 |
| 3 | £235,809 |
| 6 | £218,828 |
| 9 | £198,506 |
| 12 | £174,188 |
| 15 | £145,086 |
| 20 | £83,317 |
| 23 | £36,343 |
The value of the mortgage is £250,000 and the interest rate is 6%. Repayment has been spread over 25 years. The calculations are for illustrative purposes only and were obtained using the mortgage calculator on the MoneyHelper website.
As can be seen from the previous example, you may repay more of the capital in the last 5 years of the mortgage than in the first 12. This is of course due to the way interest is calculated. It is for this reason that we recommend to our clients that they take out insurance in the first few years of repayment in particular.
Having savings greater than your mortgage balance does not make life insurance pointless, but going without it is less risky than having no savings for a rainy day.
You have a high BMI or smoke
As paradoxical as it may sound, if you are in a higher-risk group, insurance is not always worth the cost. A high BMI (for example, a BMI of 40 or higher) can increase health risks such as heart disease and stroke, so insurers may charge higher premiums, apply exclusions or postpone cover.
Cigarette smokers are in a similar position - smokers usually pay significantly higher premiums than non-smokers, and this cost can be a deterrent. A mortgage adviser can help you compare insurers.
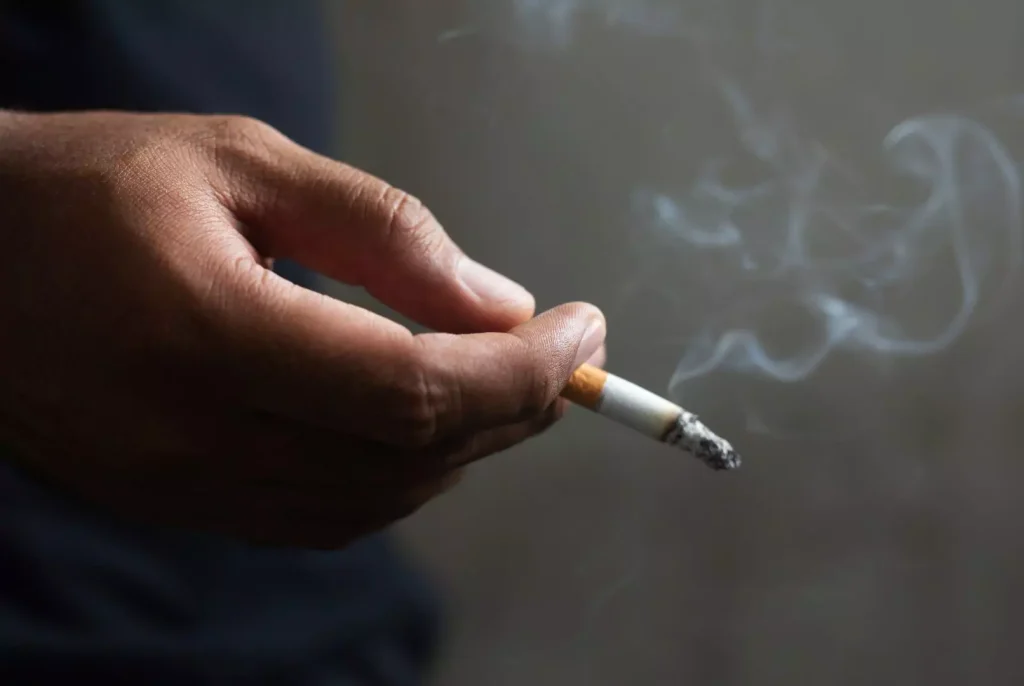
In circumstances where the proposed insurance premiums are too high for you, it is worth considering a lifestyle change and temporarily purchasing a policy for a smaller amount. After all, it is better to be insured for £20,000 than not at all.
You and your partner earn very well
Some people claim that the rich don’t need insurance. While this statement is debatable, you can actually see that having an insurance policy is more important the more vulnerable your financial situation is.
If you and your partner earn above average and the mortgage instalment is a small part of your income, a life insurance policy is less important. However, it is worth bearing in mind that you should consider the financial situation of the partner with the lower income. If one of you would not be able to pay the instalments alone, it is worth thinking about insurance.
You have no heirs or family
Although single people are a very small group of our clients, they are worth mentioning.
With no family or partner, you don’t have to worry about what will happen to your mortgage in the event of your untimely death - the mortgage would normally be repaid from your estate, for example by selling the property. However, in this situation, you should consider Critical illness cover, which can pay out if you are diagnosed with one of the conditions covered by the policy and the diagnosis meets the policy’s definition. Income protection insurance can pay a monthly benefit, typically 50-70% of your income, if you cannot work because of illness or injury, so it is also worth considering for single people.
You take out a mortgage later in life and are in good health
Life insurance premiums generally rise with age and depend on your health, so the same cover usually costs considerably more at 50 or 60 than at 30.
Insurance companies look at older applicants differently to banks - after all, the risk of developing cancer, heart attack or stroke increases with each passing year. Even athletes who take care of themselves can die prematurely.
If you decide to take out a mortgage when you are over 45, overpaying (subject to any early repayment charges) or remortgaging to a shorter term can reduce the debt faster, but it does not replace protection. Compare both options with a mortgage adviser.
Summary
Don’t get us wrong - life insurance is a very useful tool that every borrower should consider. Our post was just to make you aware that everyone’s situation is slightly different and we don’t all need a life insurance policy to the same extent.
Want to find out how much life insurance costs for you and your family? Get in touch with us. Our insurance consultations are free and talking to an agent does not commit you to anything.
FAQ
Frequently asked questions
Do banks offer better mortgages if you have life insurance?
Not really. UK lenders do not generally make life insurance a condition of a mortgage, and there is no legal requirement to take out life insurance to get a mortgage. Most lenders do, however, require buildings insurance to be in place from exchange of contracts.
Why is it worth having life insurance?
If you die, your debts are paid from your estate and a joint mortgage remains payable by the surviving borrower. A life insurance payout can help your family clear the mortgage and stay in the home, which matters most if you have dependants or a partner who could not repay the mortgage alone.
What insurances do I have to choose from?
For mortgage protection, the two main types of term life insurance are level term and decreasing term. Level term cover stays the same throughout the policy, while decreasing term cover falls roughly in line with a repayment mortgage and usually costs less.
Are there situations where it is not worth buying life insurance?
Life insurance may be less necessary if your savings exceed your mortgage balance, if you and your partner could each repay the mortgage alone, or if you have no dependants. It can also be expensive if you have a high BMI, smoke or take out a mortgage later in life, so it is worth comparing options with a mortgage adviser.
Is level or decreasing term cover better for a mortgage?
It depends on what you want the cover to do. Decreasing term cover falls roughly in line with a repayment mortgage balance and its premiums are usually lower, while level term cover leaves a fixed sum that can exceed the remaining balance, at the cost of higher premiums.