TL;DR
In short
- A Bank Rate decision does not change every mortgage payment at once: the effect depends on whether you have a fixed, tracker, discount or standard variable rate.
- Fixed-rate deals keep their agreed rate until the deal ends. New fixed-rate offers can move before a Bank Rate decision because lenders also price in market expectations and their own funding and risk costs.
- On a £100,000 repayment mortgage over 25 years, the illustrative payment rises from £527.84 at 4% to £541.74 at 4.25% and £555.83 at 4.5%.
- When a fixed deal ends, check the follow-on rate and compare a product transfer with remortgaging, including all relevant fees and charges.
- An overpayment reduces the mortgage balance, but its effect on the monthly payment or term depends on your lender and product. Keep an accessible cash buffer and check for limits or early repayment charges first.
Changes in interest rates can affect a mortgage payment, but the timing and size of the change depend on the mortgage product. A fixed-rate deal protects the agreed rate for its deal period. A tracker, discount or standard variable rate can change under the terms of the mortgage. This guide explains the difference, shows how a rate change can affect an illustrative repayment mortgage, and sets out practical steps before a deal ends.
When can an interest rate change affect your mortgage payment?
Interest rates are the price of borrowing money. Bank Rate is the Bank of England’s policy rate; it is not the same thing as every mortgage interest rate. Changes in Bank Rate can influence borrowing costs and inflation, but a mortgage rate is set by the terms of your product and, for new offers, by lender pricing.
For new fixed-rate mortgages, lenders consider market expectations about future rates as well as funding costs, credit risk and competition. That is why a new fixed-rate offer can change before, after, or without a Bank Rate decision.
Fixed, tracker and variable mortgages
The key question is which rate type applies to your mortgage:
- Fixed rate: your interest rate stays the same for the agreed deal period. Two- and five-year deals are common examples, but other fixed periods are available.
- Tracker rate: the rate follows the reference rate stated in your mortgage contract, often with a set margin. Check the contract for the reference rate, margin and timing of any change.
- Discount or standard variable rate (SVR): the lender sets the underlying variable rate. A lender may change it under the mortgage terms; it does not have to match Bank Rate point for point.
At the end of a fixed-rate deal, the mortgage normally moves to its contractual follow-on rate, often an SVR, unless you arrange another deal. It is not automatically recalculated using Bank Rate.
How much can a rate change add to a repayment mortgage?
The formula below is the standard annuity calculation for equal monthly capital-and-interest payments. It is included for transparency, but you do not need to calculate it yourself to use the examples.
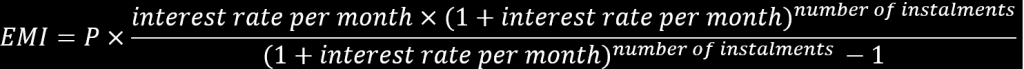
In accessible form, the formula is M = P × r / (1 − (1 + r)^−n), where:
- M is the monthly payment;
- P is the outstanding mortgage balance;
- r is the annual interest rate as a decimal, divided by 12; and
- n is the number of monthly payments remaining.
The following figures assume a £100,000 outstanding balance, a capital repayment mortgage, equal monthly payments, an unchanged illustrative annual rate, and no fees or overpayments. They are examples, not available mortgage deals or a forecast.
| Annual illustrative rate | 20 years remaining | 25 years remaining | 30 years remaining |
|---|---|---|---|
| 1% | £459.89 | £376.87 | £321.64 |
| 2% | £505.88 | £423.85 | £369.62 |
| 3% | £554.60 | £474.21 | £421.60 |
| 4% | £605.98 | £527.84 | £477.42 |
For the same £100,000 balance over 25 years, a move from 4% to 4.25% is an increase of 0.25 percentage points and changes the illustrative monthly payment from £527.84 to £541.74: £13.90 more a month. At 4.5%, the illustrative payment is £555.83, £27.99 more than at 4%.
Longer terms usually reduce the monthly payment, but can increase the total interest paid over the life of the mortgage. These examples are for capital repayment mortgages, where payments cover both interest and capital. On an interest-only mortgage, monthly payments cover interest and the capital still has to be repaid separately.
Higher rates may affect how much you can borrow when applying or remortgaging, because lenders assess affordability for the application and product. That is different from a change to your credit score, and assessment methods can vary by lender and product. For more on affordability, read our guide to how much you may be able to borrow.
What to do before your fixed deal ends
Start by checking your deal end date, current rate, follow-on rate and any early repayment charge. Estimate a range of possible payments so you can review your household budget before the change takes effect.
You may have two broad routes:
- Product transfer: take a new deal with your existing lender, if one is available and suitable.
- Remortgage: move to a new lender. This can involve product, broker, legal, valuation or early repayment charges, depending on the case.
Compare like with like: the balance, remaining term, deal period, monthly payment, total cost and all applicable fees. A lower monthly payment achieved by extending the term may mean paying more interest overall. A remortgage can be worth exploring, but whether it is suitable depends on your circumstances and the options available at the time.
Should you overpay your mortgage?
An overpayment reduces the mortgage balance, which can reduce future interest. Whether it lowers the next monthly payment, shortens the term, or does something else depends on your lender, product and instructions. Check the mortgage terms before making an overpayment: many deals set an annual allowance, and going over it during a deal period may trigger an early repayment charge.
It can also be sensible to keep cash accessible for unexpected costs rather than committing every spare pound to the mortgage. The right balance depends on your emergency savings, other borrowing and the terms of your mortgage.
If you are worried about a payment rise
Do not wait for a missed payment if you think the mortgage may become difficult to afford. Contact your lender early to discuss the options available under your mortgage. You can also find independent guidance from MoneyHelper on help with mortgage payments.
Before speaking to a lender or adviser, it can help to have your current payment, deal end date, expected follow-on rate, household income and regular outgoings to hand. This makes it easier to discuss realistic options without assuming that one solution will suit everyone.
Can anyone predict where mortgage rates will go?
No one can reliably promise where future mortgage rates will be. Bank Rate, market expectations, lender funding costs, competition and individual circumstances can all affect the options available. Instead of relying on a forecast, review your deal well before it ends and compare the terms that are actually available to you at that point.
FAQ
Frequently asked questions
Will a Bank Rate change affect my fixed mortgage?
Not during the agreed fixed-rate deal period. Your rate stays fixed until the deal ends. When it ends, the mortgage normally moves to the follow-on rate in your contract unless you arrange another deal; new fixed-rate offers may have changed in the meantime.
How much does a 0.25 percentage-point rise add to a mortgage payment?
It depends on the balance and remaining term. On the stated example of a £100,000 capital repayment mortgage over 25 years, the payment rises from £527.84 at 4% to £541.74 at 4.25%, an illustrative £13.90 a month. Fees, overpayments and later rate changes are not included.
What happens when my fixed deal ends?
Unless another deal is arranged, the mortgage normally moves to the contractual follow-on rate, often the lender’s SVR. Check that rate and any early repayment charge before comparing a new deal with your lender and remortgage options.
Can overpayments reduce my monthly payment?
An overpayment reduces your mortgage balance, but the lender and product terms determine whether the monthly payment falls, the term shortens, or another arrangement applies. Check your allowance, instructions and any early repayment charge before paying extra.
Should I switch lenders when rates change?
Not automatically. Compare a same-lender product transfer and remortgage options using equivalent balances, terms and deal periods, and include all applicable rates, fees and charges. The suitable option depends on your circumstances and the products available.