A small deposit, an imperfect credit history or a change of job can raise questions when you apply for a mortgage. None tells the whole story on its own. These seven myths about getting a mortgage in the UK explain what lenders assess and what to prepare before applying.
TL;DR
In short
- Deposit requirements and affordability are different. Higher rates can reduce how much you can borrow, leaving a larger cash gap for the same home.
- Your consumer credit score is only a guide. Lenders assess your credit history, income, commitments and their own criteria.
- Age, self-employment and a recent job change do not automatically prevent a mortgage, but the evidence and terms each lender accepts vary.
- Compare mortgage costs over the same period, including fees, repayments and the balance left to repay, rather than choosing on interest rate alone.
- Check your budget early, with adviser help if useful. A Decision in Principle is an initial indication, not a binding mortgage offer.
Getting a mortgage in the UK - application form
Myth No. 1: Higher interest rates mean I need a much larger deposit
A lender’s minimum deposit and the amount you can afford to borrow are separate questions. Loan-to-value (LTV) is the mortgage as a percentage of the property’s value: a 95% LTV mortgage normally means a 5% deposit. The lender also checks whether your income can support the repayments alongside your other spending and debts.
Higher rates can reduce the loan that passes an affordability assessment. You could therefore need more cash to buy the same home even if a lender still offers 95% LTV mortgages. A larger deposit can open up lower LTV deals, but it does not replace affordability checks.
The permanent Mortgage Guarantee Scheme, available from July 2025, supports participating lenders’ 91–95% LTV mortgages across the UK. It covers part of a lender’s potential losses; it does not guarantee that your application will be approved. A 5% deposit is an option only where you and the property meet the lender’s criteria.
Other arrangements work differently:
- Rent-based lending: Skipton Building Society’s Track Record mortgage is one product that can allow borrowing without a deposit. Applicants must meet its rent-payment, credit and wider lending requirements. It covers England, Scotland and Wales, but not Northern Ireland.
- Family support: a gifted deposit is different from a relative pledging savings or property as security. Under a family security arrangement, savings may be tied up and the pledged money or property can be at risk if the borrower fails to repay. Everyone involved needs to understand the terms and any requirement for independent legal advice.
- Joint Borrower Sole Proprietor (JBSP): another borrower’s income can support affordability without that person becoming an owner. As Family Building Society explains, supporting borrowers share repayment liability. JBSP does not itself remove the deposit requirement.
Myth No. 2: If I have a low credit score, nobody will lend me money
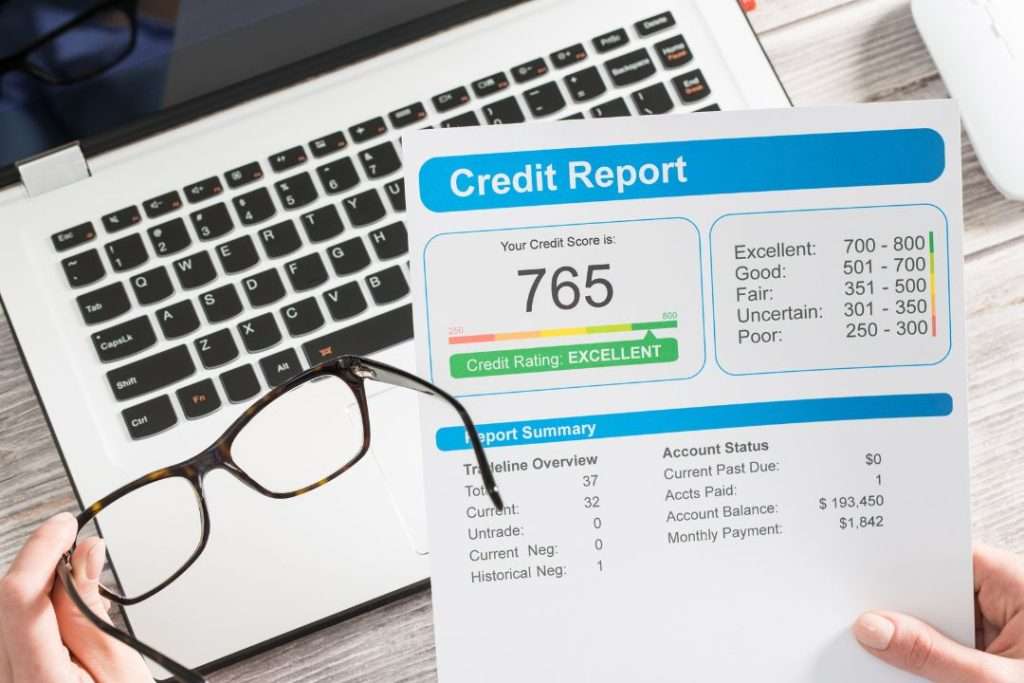
A low consumer credit score does not automatically mean rejection. The score you see from a credit reference agency is a guide, not a lender’s decision or an affordability assessment. Experian explains that there is no single universal score: lenders use credit-report information alongside application details and their own criteria. The numbers in the image above are illustrative, not a standard UK scoring scale.
Your credit history matters, including missed payments, defaults and how recently problems occurred. These can limit the lenders or deals available. Income, existing debts and regular spending also affect what you can borrow; a high score alone does not establish affordability.
Check your reports before applying and dispute inaccurate information with the relevant agency. MoneyHelper’s credit-report guidance explains how errors are investigated. Accurate negative entries cannot simply be erased because they affect an application. An adviser can help you assess your options, without promising approval or an instant improvement in your score.
Myth No. 3: If I’m 50, I’m too old to get a mortgage
Being 50 does not automatically prevent you from getting a mortgage. Lenders set their own age limits and assess whether the proposed term is affordable. If it runs into retirement, the lender may need evidence of pension and other sustainable retirement income, as well as your current earnings. Nationwide’s lending criteria illustrate why age and retirement rules need checking for the particular lender.
A longer term can reduce monthly capital repayments but increase the interest paid overall. It is not an automatic entitlement based on the difference between your age and a lender’s maximum age.
A retirement interest-only (RIO) mortgage may suit some older borrowers. You pay interest regularly and must show that those payments are affordable; the capital remains outstanding. It is usually repaid from the home’s sale when you sell, die or move into long-term care, subject to the contract. For joint borrowers, check the repayment triggers and whether the surviving borrower could maintain the payments.
RIO is different from a roll-up lifetime mortgage, where unpaid interest is added to the debt. MoneyHelper’s RIO guide explains the distinction. Suitability depends on your circumstances, not simply being over a particular age.
Myth No. 4: Being self-employed makes getting a mortgage very difficult
Self-employment changes how you evidence income; it does not automatically rule out a mortgage. Lenders consider your trading history, the sustainability of your earnings and your wider finances. Business turnover is not the same as the income a lender will use: sole-trader profit and a company director’s salary or dividends may be assessed differently.
Prepare the accounts, tax calculations and tax year overviews required by the lender, with your accountant’s help where needed. There is no single minimum trading history for every mortgage. For example, Nationwide’s standard sole-trader criteria require two years’ income and use the lower of the latest net profit or the two-year average. That is one lender’s method, not a rule for the whole market.
Open Banking access, where used, does not remove the need to meet a lender’s income-evidence requirements. Our guide to mortgages for the self-employed covers preparation in more detail.
Myth No. 5: The lowest interest rate means the cheapest mortgage
The headline rate is only part of the cost. When comparing deals, consider:
- Rate and deal length: a fixed rate stays the same during the agreed deal, such as 2, 3 or 5 years. A market rate cut does not reduce it. At expiry, you will usually move to the lender’s standard variable rate (SVR) unless you arrange another deal. Future instalments could rise or fall. Tracker payments can change with the rate they track. See MoneyHelper’s explanation of mortgage rates.
- Fees: a lender’s product or arrangement fee is separate from any broker fee you pay and any commission the lender pays the broker. Ask how advice is paid for and which charges apply. Fees added to the mortgage attract interest while they remain part of the loan.
- Early repayment charges: leaving a deal or making overpayments above its allowance may trigger a charge. Check the terms against your plans to move, switch or repay early.
Compare the same amount of borrowing, repayment method and mortgage term over the same time period. Include repayments, fees and any applicable exit charges, then compare the outstanding balance at the end of that period. A lower monthly payment alone does not prove a lower overall cost. MoneyHelper’s remortgaging guide shows how fees can change a comparison; our home-buying costs guide helps with the wider budget.
Myth No. 6: I should wait until I find a property before checking mortgages
Checking your budget early can make your property search more realistic. Consider your deposit, likely borrowing, monthly repayments and other purchase costs. You can research these yourself or speak to a mortgage adviser for help assessing lender criteria and preparing the documents.
A Decision in Principle (DIP), also called an Agreement in Principle (AIP), gives an initial indication of possible borrowing. It can help when discussing your budget with an estate agent, but it is not a binding mortgage offer or a guarantee of approval. The lender still needs to assess your full application, supporting documents and the property.
Ask whether the DIP involves a soft or hard credit search before applying. Practices vary by lender, and repeated hard searches can affect your credit record. MoneyHelper explains these checks and the limits of an agreement in principle.
Myth No. 7: I must wait to apply for a mortgage after changing jobs
A recent job change does not always require a waiting period. The lender will consider your income, contract, employment history and the evidence available. A promotion or pay rise may help affordability if the lender accepts that income, but it does not guarantee approval.
Probation and temporary contracts are not treated identically by every lender. For example, Nationwide’s employment criteria allow consideration during probation and in certain new-job or future-start situations, with specified evidence such as a payslip, signed contract or appointment letter. Other lenders may require a different history or documents.
Check the relevant criteria before applying, particularly if your income varies or your contract has an end date. Our guide to mortgages after changing jobs explains the issues to discuss with a lender or adviser.
Summary
Getting a mortgage depends on the lender’s assessment of you, the loan and the property. Start with a realistic budget, check your credit reports and gather income evidence before comparing suitable deals. If you would like help understanding your options, book a free initial consultation. Ask about any fees for further advice or arranging the mortgage before proceeding.
FAQ
Frequently asked questions
Can I get a mortgage with a 5% deposit?
It can be possible if you and the property meet the lender’s criteria, including affordability and credit checks. The Mortgage Guarantee Scheme supports participating lenders’ lending at high LTV; it does not guarantee your approval. Your affordable borrowing may still leave you needing a larger deposit for a particular home.
Does a low credit score automatically mean a mortgage rejection?
No. A consumer score is a guide, while lenders assess credit history, income, spending and their own criteria. Missed payments or defaults can limit your options. Check for errors, but do not assume accurate negative entries can be removed.
Should I speak with an adviser before finding a property?
It can help you understand your budget and prepare, although you can also research mortgages yourself. A Decision in Principle is an initial indication, not a binding offer. A full application and checks on you and the property are still needed; ask whether the initial credit search is soft or hard.
Does being self-employed make getting a mortgage harder?
Being self-employed means providing the income evidence a lender requires, which may include accounts, tax calculations and tax year overviews. Trading history and the way income is assessed vary by lender. Business turnover is not the same as assessed income, and self-employment does not automatically mean you can borrow less than an employed applicant.
Does the lowest interest rate always mean the cheapest mortgage?
No. Compare the same borrowing, repayment method and term over the same period, including fees, repayments, any early repayment charges and the balance left to repay. A fixed-rate deal can have a low headline rate but higher overall costs once fees are included. Fees added to the loan also accrue interest.