TL;DR
In short
- Fracture cover pays a fixed lump sum if you suffer an injury listed in the policy, which you can use towards costs or lost income while you recover.
- Fracture cover is commonly offered as an optional add-on to life insurance, critical illness cover, income protection or personal accident cover.
- The amount paid depends on the type of injury, and many policies also set a maximum amount payable each year.
- Exclusions vary by insurer and may include injuries from high-risk sports and fractures caused by osteoporosis.
- Check the list of covered injuries, the amounts and the exclusions in the policy’s key facts before you buy.
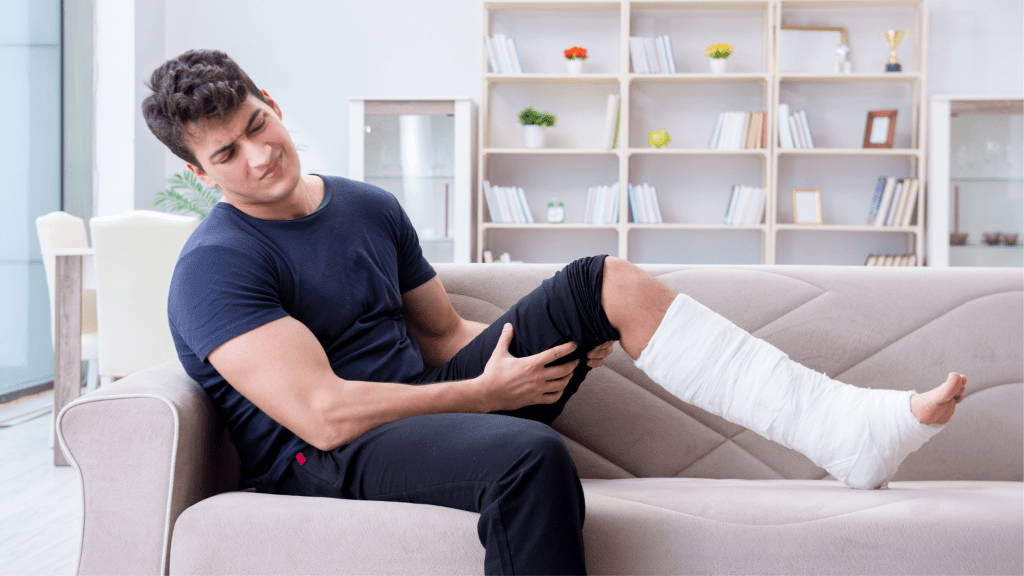
A broken bone or other serious limb injury is painful, and if your job is physical it can also stop you working for a while. If you are a courier, a warehouse worker, work on a construction site or do another job that needs a lot of movement and strength, it is worth considering whether fracture cover would help.
How does fracture insurance work in the UK?
Fracture cover pays a fixed lump sum if you suffer an injury listed in the policy, which you can use towards costs or lost income while you recover. Typically, the insurer pays a lump sum, which may help with expenses during your recovery.
Types of fracture insurance
Fracture cover is commonly offered as an optional add-on to life insurance, critical illness cover, income protection or personal accident cover.
Insurers such as Aviva and Zurich offer fracture cover as an optional add-on to some protection policies, and Cirencester Friendly offers a fracture benefit as an optional extra with its income protection. Some insurers charge a fixed monthly amount for a fracture add-on, for example around £4 a month, but check the current price when you apply. Published benefit levels differ between insurers, for example (checked October 2026):
- Zurich: from £2,000 to £6,000 depending on the injury, up to £6,000 in total per policy year.
- Aviva: up to £6,000 depending on the fracture.
- Cirencester Friendly: up to £1,500 for a fracture to one of the listed bones, claimable once every 12 months, as part of an optional add-on to its income protection.
The amount paid depends on the type of injury, and many policies also set a maximum amount payable each year. Some policies also cover certain joint dislocations and ligament or tendon ruptures, while others cover only bone fractures.
Some insurers include fracture cover as standard with their income protection; Royal London is one example. With some companies, purchasing fracture insurance is only possible through a broker, such as Extend Finance.
Fracture cover within personal accident insurance
Fracture cover can also come as part of personal accident insurance. Some personal accident policies offer several levels of cover, and some can also cover your children. The broader the cover you buy, the higher the premium, but also the higher the benefit amount.
Many policies pay different amounts depending on which bone is broken or how serious the injury is, and limits differ between policies. When choosing fracture cover for yourself or your family, check which injuries are listed and how much is paid for each. You can find the list of covered injuries, the amounts and the limits in the document called Key Facts.
Exclusions in fracture insurance
Exclusions vary by insurer. Injuries from high-risk sports and activities may be excluded because they are more likely to lead to a claim. For example, Zurich’s Multi-Fracture Cover does not pay for injuries from taking part in or training for sports such as:
- Mountain biking;
- Boxing, martial arts or cage fighting;
- Rugby;
- Horse riding;
- Motor sport.
It also does not pay for injuries caused by osteoporosis.
The exact composition of the list depends on the insurance company. If you take part in a sport with a higher risk of injury, let us know so we can check whether suitable cover is available and explain any relevant exclusions or restrictions. Some policies do not cover smaller fractures; for example, Zurich’s Multi-Fracture Cover does not pay for broken fingers, thumbs or toes.
Planning to buy fracture insurance in the UK? Be sure to contact us. You do not pay Extend Finance any fees for reviewing your insurance needs, providing insurance advice or arranging a policy. If you take out a policy through us, we receive commission from the insurer. You only pay the insurance premium for your chosen policy.
FAQ
Frequently asked questions
How does fracture cover work in the UK?
Fracture cover pays a fixed lump sum if you suffer an injury listed in the policy, which you can use towards costs or lost income while you recover. The amount paid depends on the type of injury, and many policies also set a maximum amount payable each year.
Can I buy fracture cover on its own?
Fracture cover is commonly offered as an optional add-on to life insurance, critical illness cover, income protection or personal accident cover. Some insurers include fracture cover as standard with their income protection; Royal London is one example.
How much does fracture cover pay out?
It depends on the insurer and the injury. For example, Zurich pays from £2,000 to £6,000 depending on the injury, up to £6,000 in total per policy year. Check the list of injuries and amounts in the policy’s key facts.
What is usually excluded?
Exclusions vary by insurer. Injuries from high-risk sports such as mountain biking, boxing, rugby, horse riding or motor sport, and fractures caused by osteoporosis, may be excluded. Some policies do not cover smaller fractures such as broken fingers, thumbs or toes.
Is fracture cover worth it?
It may be worth considering if your job is physical and a broken bone could stop you working for a while. Because it pays a fixed lump sum for listed injuries, compare the amounts paid for each injury, any annual limit and the exclusions before you buy.