TL;DR
In short
- No one will be surprised to learn that the interest rate on a mortgage is the most important selection criterion it affects both the monthly instalment and the total amount of interest you will have to pay.
- The fixed rate period has a big impact on the interest rate of the mortgage.
- Most mortgages with very low interest rates have a commission and other upfront costs both valuation fees and cashbacks have to be taken into account.
- An early repayment charge (ERC) is an additional charge for early repayment of a mortgage.
- Remember that your creditworthiness may vary from bank to bank .
Choosing a mortgage offer in the UK involves comparing products from lenders with different eligibility rules, rates and fees. Tailoring a mortgage to your individual needs requires a lot of knowledge and it doesn’t just come down to finding the product with the lowest interest rate. Of course, this is one of the most important considerations in determining the attractiveness of an offer, but there are other factors to take into account as well - otherwise, buying a home could end up being much more expensive than you originally anticipated.
In this article, we will discuss in detail the most important aspects of mortgages that affect their attractiveness and the tailoring of the offer to the customer. This way, you will be able to get a good understanding of what your mortgage broker is talking about and make an informed decision together with them.
Interest rate
No one will be surprised to learn that the interest rate on a mortgage is the most important selection criterion - it affects both the monthly instalment and the total amount of interest you will have to pay.
Mortgages in the UK are divided into several types, but our clients most often choose fixed-rate products. The principle behind these is that for the first 2, 3 or 5 years of the contract, the interest rate is fixed and unchanging, but after that, they move to a standard variable rate (SVR).
When choosing an offer, it is worth looking at both the concessionary rate and SVR. Refinancing your UK mortgage is a standard procedure that avoids the less favourable variable rate, but there are situations where a remortgage will be less cost-effective than temporarily paying higher instalments. For this reason, it is worth analysing the terms of the entire repayment, not just the initial period.
Rates change frequently. Compare products using the same loan amount, property value, term, repayment method and comparison period. Include fees, cashback and the balance remaining at the end, rather than treating a historical headline rate as a current offer. The MoneySuperMarket comparison tool can illustrate available products, subject to eligibility and current terms.
Length of the preferential interest period
The fixed-rate period affects payment certainty and flexibility. Compare the total cost over a consistent period and consider your plans, affordability and early repayment charges. Moving house does not by itself determine whether a two- or five-year fix is suitable. Remortgaging or porting may be possible, but both depend on eligibility and the terms available at the time.
Commission
Most mortgages with very low interest rates have a commission and other upfront costs - both valuation fees and cashbacks have to be taken into account. However, it is worth remembering, all these costs need to be weighed against the interest rate and only on this basis can you estimate what is more worthwhile.
Early Repayment Charge
An early repayment charge (ERC) is an additional charge for early repayment of a mortgage. Although there are mortgage offers without ERCs, they are a distinct minority. Overpayment charges may or may not be a significant factor. Indeed, it is important to remember that many borrowers do not plan to repay their properties earlier than necessary.
As we have already mentioned, there are mortgage offers without an ERC, although there are relatively few of them. The charge may depend on the amount repaid early, the applicable rate and the overpayment allowance; the mortgage offer sets out the terms. Check the ERC rate and the amount to which it applies under your product terms; it is not generally a percentage of the property sale price. Include it in any sale or remortgage comparison.
As with commissions, it is worth carefully calculating when it pays to take a higher-interest mortgage from the ERC and when it does not make sense to do so. Two examples will perfectly illustrate this:
Thomas took out a mortgage for £300,000 at a fixed rate for five years, but after three years he was offered a job with a salary £6,000 a year higher. In his case, the ERC is 3%, which he has to pay on £260,000 - so it is £7,800. In this situation, relocation will not be as profitable because, ignoring the standard costs of buying a flat in the UK, the hero of the example will use a large part of his earnings to repay the penalty from the bank.
Anna, fearing the situation described in Thomas’ example, decided to choose a mortgage offer with a fixed interest rate for 2 years and with an ERC charged for only two years. Her illustrated ERC period ends after 24 months, but a later remortgage is not guaranteed: it depends on her circumstances, the property and lender criteria at that time. However, Anna has no plans to move and didn’t want to change banks before 24 months - in her case, it was the timing of the ERC drawdown that mattered, not its rate.
Approach to calculating creditworthiness
Remember that your creditworthiness may vary from bank to bank. Different institutions have their own ways of calculating affordability - some will look more favourably at entrepreneurs, others will give better terms to people on a contract of employment. When assessing a customer’s affordability, banks mainly consider their net income, fixed expenses (including debt-to-income ratio) and credit history.
The biggest differences when calculating affordability are at the stage of assessing income from overtime and other non-permanent sources of income - while some lenders will not take these into account at all, others will give you a significantly higher mortgage based on them.
Strictness of credit risk assessment
This is, in a way, a development of the previous point - lenders very often target a specific group of customers, such as people with a very low risk of bankruptcy, veterinarians or people with First Time Buyer status. This approach allows them to promote their services using whisper marketing to a particular social group and to offer better repayment terms, as the analysts working for these companies have a much better understanding of the situation of the niche in question - this is important, as the income structure of a vet will be very different to that of a truck driver or an accountant.
As a result, some banks will offer lower interest rates, but under stricter mortgage conditions. Such institutions are targeting customers with a better and more stable financial situation - this is part of their business strategy, because instead of entering into a partnership with a riskier customer (admittedly with a higher rate of return), but being exposed to the consequences, these banks prefer to give a cheaper mortgage, but to a confident customer.
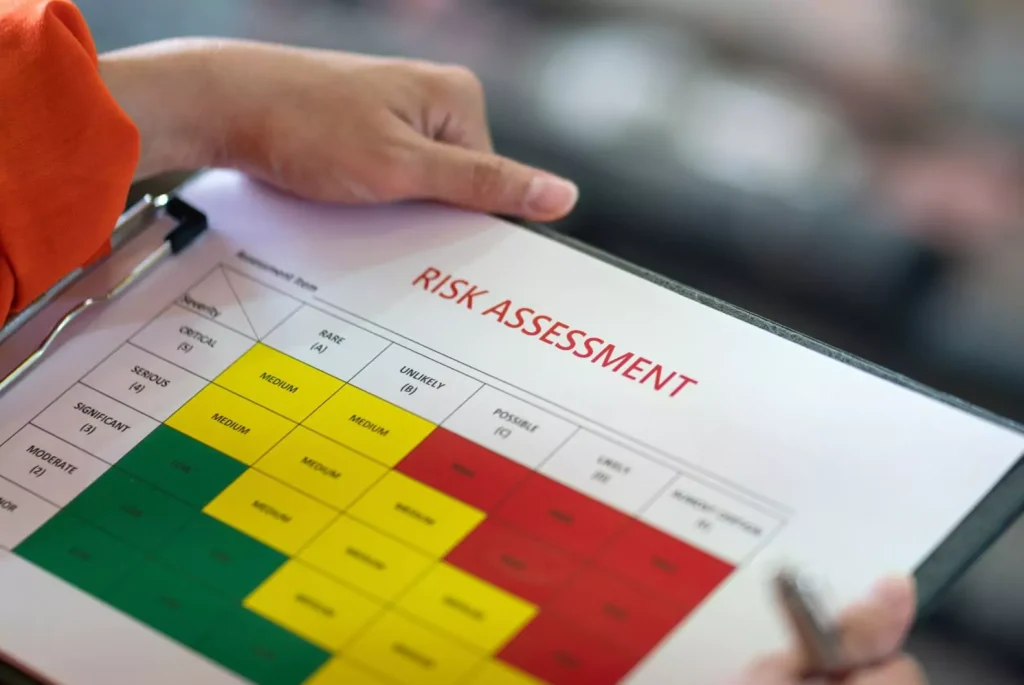
Of course, this does not mean that it is impossible to find an attractive offer on attainable terms. In this you need knowledge of the market and the mechanisms used by the banks. A person who can definitely prove himself here is a credit broker, for example from Extend Finance. A professional, thanks to his knowledge and experience in the sector, will be able to match bank offers to your possibilities and compare suitable options, subject to your circumstances and lender criteria.
Property requirements
Sometimes mortgage rates can be different for different types of property. You can come across all sorts of rules. Some banks, for example, will not grant a mortgage for:
-
Dwellings above shops or restaurants;
-
Houses of unusual materials;
-
Houses of non-standard construction.
The age of the property may also be important and if this is too high, the bank may refuse the mortgage or expect additional technical expertise.
In addition, you may come across the term ‘green mortgage’. This is the name given to mortgages that have a lower interest rate if they are taken out for a property with an EPC (Energy Performance Certificate) grade A or B (the highest grades). This is a document that shows how energy efficient a property is - the higher the energy rating, the less energy is needed to heat and cool the house, and this of course translates into the environment.
Timing of the Decision in Principle
A Decision in Principle is an initial indication, not a final mortgage offer or confirmation that funds are ready. For an auction, establish the completion deadline and arrange appropriate finance and legal checks before bidding; a DIP alone does not make a bid safely fundable.
From our experience, we can say that the time it takes to issue a decision in principle at a particular bank is strongly dependent on the current market situation. When a lender introduces a new, favourable offer, hundreds of applications flow into the bank within a few days, which can drastically increase the waiting time for a decision. This is much less pronounced at large financial institutions, but the terms and conditions they offer can be worse.
Aid schemes
First Homes is available only in England, for eligible first-time buyers aged 18 or over. It has income limits, a minimum mortgage requirement, property price limits and potentially local criteria. All joint buyers must qualify. Check the full current rules rather than assuming that not currently owning a property is sufficient. See also first-time buyer guidance.
Another group are those wishing to take advantage of the government’s Shared Ownership scheme. This involves the client buying some part of the property and renting the rest from an institution. Some banks specialise in mortgages specifically for these clients, but there are not many on the market.
The country you live in
The offers from banks in the UK are mostly similar, but this is not something to suggest. The bank will, of course, look at the location of your property - this is important both from the perspective of risk or the potential for an increase in the price of the object securing the mortgage, but also logistics. While many financial institutions operate across the UK, there are some that limit their reach to just one county. Local banks often have really good mortgage offers, but these may only be available to a few.
FAQ
Frequently asked questions
Interest rate?
No one will be surprised to learn that the interest rate on a mortgage is the most important selection criterion it affects both the monthly instalment and the total amount of interest you will have to pay.
Length of the preferential interest period?
The fixed rate period has a big impact on the interest rate of the mortgage.
Commission?
Most mortgages with very low interest rates have a commission and other upfront costs both valuation fees and cashbacks have to be taken into account.
Early Repayment Charge?
An early repayment charge (ERC) is an additional charge for early repayment of a mortgage.
Approach to calculating creditworthiness?
Remember that your creditworthiness may vary from bank to bank .