TL;DR
In short
- A standard residential mortgage may be possible for a habitable home needing cosmetic work, subject to the valuation, condition, affordability and lender criteria.
- A property needing essential repairs or major redevelopment may need specialist finance or more upfront funds; the lender may also retain part of a mortgage until repairs are complete.
- A bridging loan is short-term secured borrowing. It needs a credible exit strategy, and refinancing or an extension is never guaranteed.
- Before buying, assess the survey findings, professional quotations, contingency, finance costs and any need for temporary accommodation.
- Homeowners raising money for works can compare a further advance, remortgage, second charge mortgage, savings and an unsecured personal loan.
Buying a home that needs renovation can be a major project, but the finance depends on the property’s condition and the work planned. A habitable home needing cosmetic improvements may be suitable for a standard residential mortgage, subject to the valuation, affordability and the lender’s criteria. A property requiring essential repairs or major redevelopment can be treated differently, and may need specialist finance or more cash before work starts.
Why are banks reluctant to lend to buy houses for renovation?
Lenders and valuers consider whether a property is suitable security for the loan. Serious defects, uncertainty about the work required or a property that may be difficult to sell can affect the valuation and the available lending options.
The valuation is not a guarantee that the property will be worth more after the works. It can identify condition issues and, depending on the lender, part of the mortgage may be retained until necessary repairs are completed. If that happens, you may need separate funds to complete the work before the retained amount is released.
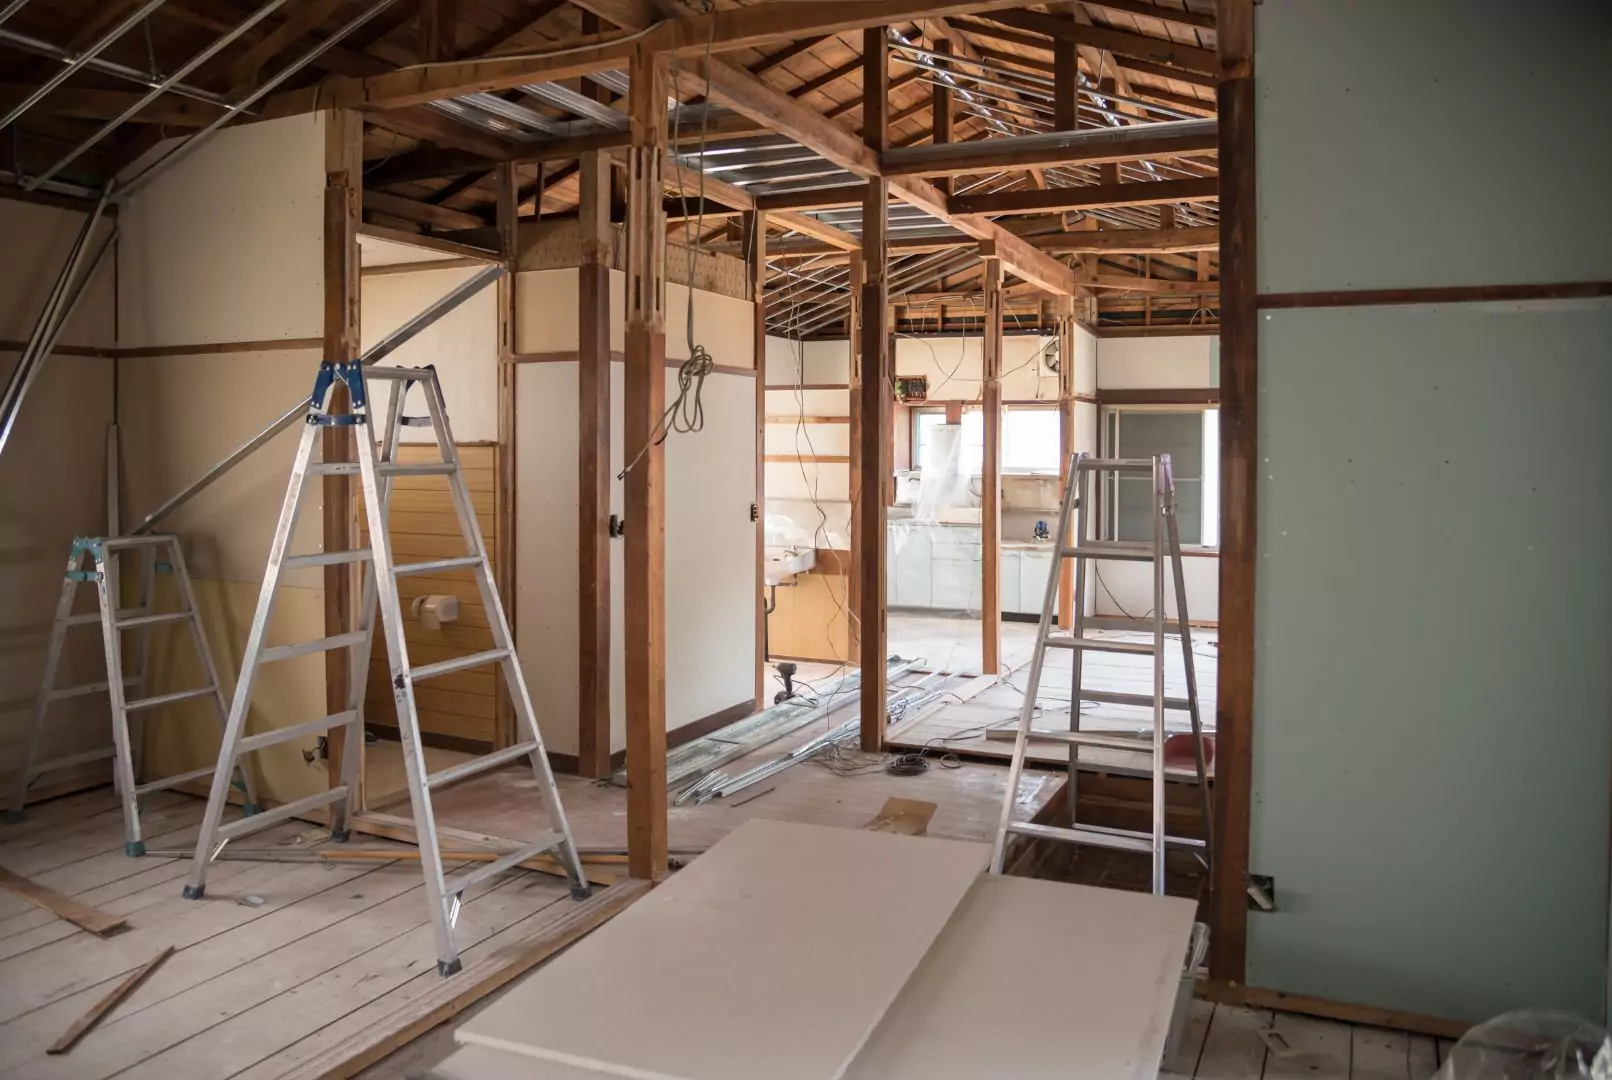
The level of work matters. Redecoration or an older kitchen is different from a home without essential services, with serious structural concerns or requiring major redevelopment. Always allow for the possibility that the survey, valuation or quotations identify further work.
What requirements must a property meet to get a mortgage on it?
There is no single UK-wide statutory checklist that decides mortgage eligibility. Lenders’ and valuers’ requirements vary, but they may consider whether the home has working facilities and services, a sound structure and suitable insurance cover. These are examples, not an exhaustive legal test.
-
Kitchen and bathroom facilities with running water;
-
Working heating and electricity services;
-
The condition and any serious structural concerns;
-
Whether the property is insurable and marketable;
Construction type and marketability can also affect a lender’s decision, particularly for non-standard construction. Your conveyancer will check the title, rights of access and, where relevant, whether a lease is acceptable to the lender. Lease criteria differ by lender, property type, loan-to-value and jurisdiction, so an individual lease term is not a universal rule.
If you are unsure how the condition may affect your application, ask a mortgage adviser about the criteria of the lenders they can consider.
Are there any banks that provide loans for the purchase of properties for renovation?
The right finance depends on the property’s condition, the scope of the work and how it will be repaid. A standard residential mortgage may be possible for a habitable home, while a project involving essential repairs or redevelopment may call for a specialist product.
Bridging loan
Bridging finance is short-term secured borrowing that may be considered for a purchase or project that cannot proceed with ordinary residential finance. The lender will assess the security and a credible exit strategy, such as a sale, refinance or other confirmed funds.
Interest may be serviced each month, retained from the advance or rolled up, depending on the product. The capital is normally due at the agreed end date. A detailed cost estimate and renovation plan can help you understand the funding needed, but they do not guarantee an offer or a successful exit.
Refinancing is a separate application, subject to future eligibility and valuation, and an extension is not guaranteed. Delays, cost overruns or a failed sale or refinance can leave the debt unpaid and put the secured property at risk. Bridging for a home you will occupy and borrowing for investment or business purposes can have different regulatory status, so ask an adviser or lender which applies to your circumstances.
Refurbishment mortgage
Specialist renovation finance is not one uniform product. Some products can support extensive renovation and use staged releases linked to the property’s value or progress; their criteria may also include project or energy-performance requirements.
The lender may require a detailed cost estimate, a plan for the work and inspections or valuations during the project. Staged funding can leave an early-work cash gap, and it does not mean that every purchase or building cost will be covered. Pricing, maximum LTV, fees and the net funds available depend on the lender, the property and the project.
Before applying, compare the product terms, your available cash and the risks if the project takes longer or costs more than expected. An adviser can discuss possible options, subject to suitability and lender approval.
Is it worth buying a property to renovate in the UK?
Buying a renovation property can work for some buyers, but it needs careful planning. Start with the purchase price, survey findings, professional quotations, a contingency for unexpected work, finance costs and any need for temporary accommodation.
Choose a survey that is appropriate to the property and the work proposed. A lender’s valuation is not a substitute for an independent condition survey. It can also be sensible to get specialist advice where the survey identifies a particular concern.
The transaction and property rules can differ across the UK. Our guides to buying in Wales and Scotland explain those locations in more detail; do not assume that a rule from one nation applies in another.
Raising money for renovation on a home you already own
If you already own the home, raising money for renovation is a separate decision from buying a renovation property. Options can include a further advance from your current lender, a remortgage, a second charge mortgage, savings or an unsecured personal loan. Your mortgage, insurer, lease and any applicable permissions may place requirements on substantial work, even when your payments are up to date. Check what applies to your property, project and UK nation before you begin.
For all borrowing options, lenders assess affordability and creditworthiness. Compare repayments, fees, early repayment charges and the total cost of borrowing, not just the monthly payment.
Second charge mortgage
A second charge mortgage is additional borrowing secured on your property. It is not necessarily smaller or low-cost. The equity available is the property’s value minus the secured debt against it, and the lender will assess the application on its own terms.
Spreading borrowing over a longer term can reduce the monthly payment, but it can increase the total interest paid. It does not change the amount borrowed relative to your income. Your home may be repossessed if you do not keep up repayments on a mortgage or other loan secured on it.
Remortgage
When planning major works, you may also want to consider remortgaging. A remortgage replaces your existing mortgage with a new one, potentially with additional borrowing. Whether it is available or suitable will depend on the lender’s assessment, the product terms and your circumstances.
It is not automatic that a remortgage will be cheaper, or that the new monthly payment will be lower. Compare the full costs and take advice before deciding.
Unsecured personal loan
An unsecured personal loan is separate from your mortgage and does not use your home as security. Its rate, term, amount and availability depend on the lender and your circumstances. It may suit some smaller projects, but you should still compare the repayments and total cost with the alternatives.
Summary
Every renovation project is different. Before committing, understand the property’s condition, the likely scope and cost of the work, your finance options and the consequences if the project is delayed.
If you are considering a mortgage for a renovation property, contact us to discuss possible options. Any recommendation is subject to suitability and lender approval.
FAQ
Frequently asked questions
Why are banks reluctant to lend to buy houses for renovation?
A standard residential mortgage may be possible for a habitable home needing cosmetic work, subject to the valuation, affordability and lender criteria. Serious defects or major redevelopment can affect the available options.
What requirements must a property meet to get a mortgage on it?
There is no single UK-wide checklist. Lenders and valuers may consider the property’s condition, working services, structure, insurability, construction and marketability, as well as title and lease issues.
Are there any banks that provide loans for the purchase of properties for renovation?
For a habitable home, a standard mortgage may be possible. A property requiring essential repairs or major redevelopment may need specialist finance, a retention arrangement or additional cash before work starts.
Is it worth buying a property to renovate in the UK?
Assess the survey findings, professional quotations, contingency, finance costs and any need for temporary accommodation. A lender valuation is not a substitute for an independent condition survey.
How can I finance renovation on a home I already own?
For a home you already own, options can include a further advance, remortgage, second charge mortgage, savings or an unsecured personal loan. Compare the full cost and remember that secured borrowing puts your home at risk if repayments are missed.