TL;DR
In short
- A joint mortgage involves the joint application and subsequent repayment of a mortgage taken out to purchase a property, for example by two partners or by parents with their adult child.
- Lenders assess applicants’ joint income and outgoings together rather than simply adding up what each of you could borrow alone, and the maximum number of applicants and the maximum age limit vary by lender.
- Each borrower is liable for the full mortgage if a co-borrower stops paying, and missed payments can affect every borrower.
- Ownership can be arranged as joint tenants or tenants in common (terms used in England and Wales), or through a joint borrower sole proprietor mortgage, where only one borrower owns the property.
- In England and Northern Ireland, buying jointly with someone who has owned a home before means you cannot claim Stamp Duty Land Tax first-time buyer relief, and if that person still owns another residential property, the 5% higher rates for additional dwellings will usually apply.
Everyone wants to have their own home, but getting to that state is not always easy. Buying a home in the UK requires a relatively large amount of money, which is usually raised through a mortgage repaid over many years - some lenders offer terms of up to 40 years on a repayment basis. Although young borrowers in particular can spread the repayment of their commitment over many years, they often find that their creditworthiness is still too low. Banks are aware of this and that is why joint mortgage products are available on the market. Let us take a look at them.
What is a joint mortgage?
In the simplest terms, a joint mortgage involves the joint application and subsequent repayment of a mortgage taken out to purchase a property. The application can be made by either two partners or parents together with their adult child.
The maximum number of applicants depends on the lender: some lenders accept more than two people, while others only offer joint mortgages to two.
Why apply for a joint mortgage?
When assessing your mortgage application, analysts employed by the bank will estimate your affordability, i.e. the amount you can borrow to purchase the property. This is derived from three factors:
Income of the borrower(s)
Earning, for example, £2,000 a month, or £24,000 a year, you will inevitably not be able to apply for a mortgage with an instalment of £2,500. When the joint income of several applicants is taken into account when calculating affordability, the total income assessed is higher, which may allow you to borrow more.
Disposable income, i.e. the difference between income and expenditure
How much you can borrow is also affected by your expenses. The more subscriptions and other fixed commitments you have, the lower your affordability will be. However, if you share expenses with a loved one, for example because you live together, there is a larger sum left in your budget that can be used to pay off your new home.
If you apply with your parents, the lender will assess their income, outgoings and credit history too, and their age may limit the maximum term the lender will offer.
Repayment period
The joint mortgage has no direct bearing on the repayment period, and if it does, it is likely to reduce the maximum repayment period. However, this is an extremely important parameter in terms of affordability itself, as the more years, the less borrowed capital you will have to repay each month.
In sum, a joint mortgage can allow you to borrow more than you could alone (source: Lloyds), which may let you buy a more expensive property or repay over a shorter term.
How is creditworthiness calculated for a joint mortgage?
Lenders assess applicants’ joint income and outgoings together, so the amount you can borrow is based on your combined circumstances rather than simply adding up what each of you could borrow alone. You will also need to be able to repay the mortgage within the lender’s maximum age limit for the oldest borrower - this varies by lender, for example 75 at some lenders and higher at others.
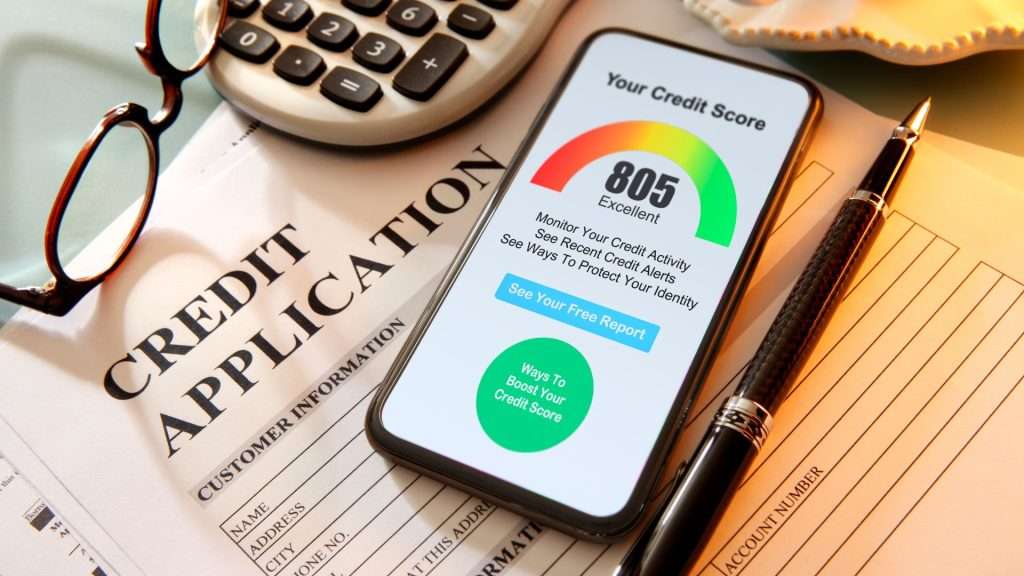
For the sake of precision, let us add that some banks will only take into account the income of the two highest-earning borrowers. Each lender sets its own rules on this, so a mortgage broker can help you compare different lenders’ criteria.
What about the credit score?
Your credit history, as recorded by the credit reference agencies, is an important factor in whether a lender will offer you a mortgage. Your credit score can also affect how attractive the deals available to you are. If you apply jointly, the lender checks each applicant’s credit history, and one applicant’s poor credit history could affect whether the application is accepted. For this reason, if you are applying for a mortgage as a couple or a married couple, it is worth considering whether the person with the poorer credit history is able to improve it, for example by keeping up small regular payments on time.
What do I need to do to apply for a joint mortgage?
Each applicant must meet the lender’s lending criteria, including its minimum age, and the lender will check each applicant’s credit history, income and outgoings. Before the bank decides to grant you a mortgage, factors such as your credit score, credit cards held, employment history, income and expenses will be analysed. At the application stage, each applicant will need to provide their own personal, income and credit details.
Contact your mortgage advisor to arrange a free, no-obligation meeting. We will explain to you step-by-step what a joint mortgage application entails in a matter of minutes.
Joint mortgages and first-time buyer status
First-time buyers sometimes apply with someone else, such as a partner or parent, to increase the amount they may be able to borrow. In England and Northern Ireland, Stamp Duty Land Tax first-time buyer relief is only available if you and everyone you are buying with are first-time buyers, so buying jointly with someone who has owned a home before (such as a parent) means you cannot claim it. If that person still owns another residential property, the purchase will usually also attract the 5% higher rates for additional dwellings. Scotland (Land and Buildings Transaction Tax) and Wales (Land Transaction Tax) have their own rules.
As in some cases the savings can be as much as £5,000, losing first-time buyer relief can be painful. Losing the relief may still be worth it if a joint application is what makes the purchase affordable, so compare the cost with your other options, including continuing to rent. One exception to this rule is the Joint Borrower Sole Proprietor Mortgage, which we will discuss later in this article.
Under a joint mortgage, do all borrowers have the same ownership rights?
Broadly speaking, there are three main types of ownership arrangements for joint mortgages. Joint tenants and tenants in common are terms used in England and Wales; property law in Scotland differs.
Joint tenants - equal sharing of ownership
This arrangement can suit partners who live in one household and share expenses between them. In this legal state, both tenants gain equal ownership rights over the property. If one owner dies, their share passes automatically to the surviving owner(s).
Tenants in common - unequal distribution of shares
In the case of tenants in common, each borrower may have a different number of shares in the home being repaid. This situation is more likely to occur when further family members are involved in the repayment. You can leave your share of the property to someone else in your will.
It is advisable to get legal advice and record how you will share ownership, for example in a declaration of trust.
Joint borrower sole proprietor - shares in the hands of one of the borrowers
In the case of a joint borrower sole proprietor mortgage, this is a situation where the mortgage is repaid by several people, for example parents and their adult child. The responsibility for settling the obligations lies with all the borrowers, but only one of them becomes the owner of the property.
Later on, the owner may be able to ask the lender to remove the other borrowers from the mortgage. This is not automatic: the lender will carry out an affordability assessment to check that the owner can afford the mortgage on their own. Not all lenders offer joint borrower sole proprietor mortgages, and their criteria vary. Deposit requirements depend on the lender.
This structure also matters for first-time buyer relief. Under SDLT rules in England and Northern Ireland, first-time buyer relief is only available if everyone buying the property is a first-time buyer. Because only the named owner is buying the property, SDLT first-time buyer relief in England and Northern Ireland depends on that owner’s status; the other borrowers’ ownership history does not affect it.
Under a joint mortgage, do all borrowers have to pay equal parts of the instalment?
Borrowers do not have to pay equal parts of the instalment unless they agree to do so. How you split the monthly payments between you is up to you, but each borrower is responsible for the mortgage, so if one person stops paying, the others must make up the full payment. This means that, with a joint mortgage, you can, for example:
-
Pay instalments on a 50/50 basis with your partner;
-
Agree that only one person pays the instalments;
-
Apply for a mortgage with your parent, become the sole owner of the property and cover all instalments yourself, with your parent’s income also taken into account (JBSP mortgage).
Advantages and disadvantages of joint mortgages
As is usually the case with finance, every product has both advantages and disadvantages. Start with the reasons why a joint mortgage is worth considering:
You can borrow more or spread your mortgage over fewer years
The main advantage of a joint mortgage is that, because the lender assesses your combined income and outgoings, you may be able to borrow more than you could alone. This is of considerable importance for young people as well as those who want to pay back as little as possible to the bank - the sooner you pay off your commitment, the less interest you will pay.
You have the formal support of relatives to repay the mortgage
When applying for a mortgage, each applicant takes full responsibility for repayment. This means that if an event occurs that temporarily prevents you from paying your instalments, another borrower may be able to cover the payments for a while, but every borrower remains liable for the whole mortgage and missed payments can affect every borrower.
As we have already mentioned, the joint mortgage unfortunately also has disadvantages. The main disadvantages are:
You are each responsible for the whole debt
Each borrower is liable for the full mortgage if a co-borrower stops paying, and a joint mortgage links you financially on your credit files, so a co-borrower’s credit history can affect your future applications.
Possibility of losing First Time Buyer status
If the person you are buying with owns or has owned a property before, you will not be able to claim SDLT first-time buyer relief in England and Northern Ireland. This translates into several hundred or even several thousand pounds in cash that you will have to prepare for the fees and taxes associated with buying a home in the UK. If they still own another home when you buy, the higher rates for additional dwellings will usually apply as well.
Remortgaging can be more complicated
Remortgaging in the UK, or swapping an old mortgage for a new, better one, can be more complicated when several people are involved in the repayment. When you remortgage, all borrowers need to agree, and each must meet the new lender’s criteria.
Read more:
FAQ
Frequently asked questions
What is a joint mortgage?
In the simplest terms, a joint mortgage involves the joint application and subsequent repayment of a mortgage taken out to purchase a property.
Why apply for a joint mortgage?
When the joint income of several applicants is taken into account when calculating affordability, the total income assessed is higher, which may allow you to borrow more. This may let you buy a more expensive property or repay over a shorter term.
How is creditworthiness calculated for a joint mortgage?
Lenders assess applicants’ joint income and outgoings together, so the amount you can borrow is based on your combined circumstances rather than simply adding up what each of you could borrow alone. Some lenders only take into account the income of the two highest-earning borrowers, and the oldest borrower must be able to repay the mortgage within the lender’s maximum age limit, which varies by lender.
What do I need to do to apply for a joint mortgage?
Each applicant must meet the lender’s lending criteria, including its minimum age, and the lender will check each applicant’s credit history, income and outgoings. At the application stage, each applicant will need to provide their own personal, income and credit details.
Can I still get first-time buyer stamp duty relief with a joint mortgage?
In England and Northern Ireland, Stamp Duty Land Tax first-time buyer relief is only available if you and everyone you are buying with are first-time buyers, so buying jointly with someone who has owned a home before means you cannot claim it. With a joint borrower sole proprietor mortgage, only the named owner is buying the property, so the relief depends on that owner’s status. Scotland and Wales have their own rules.